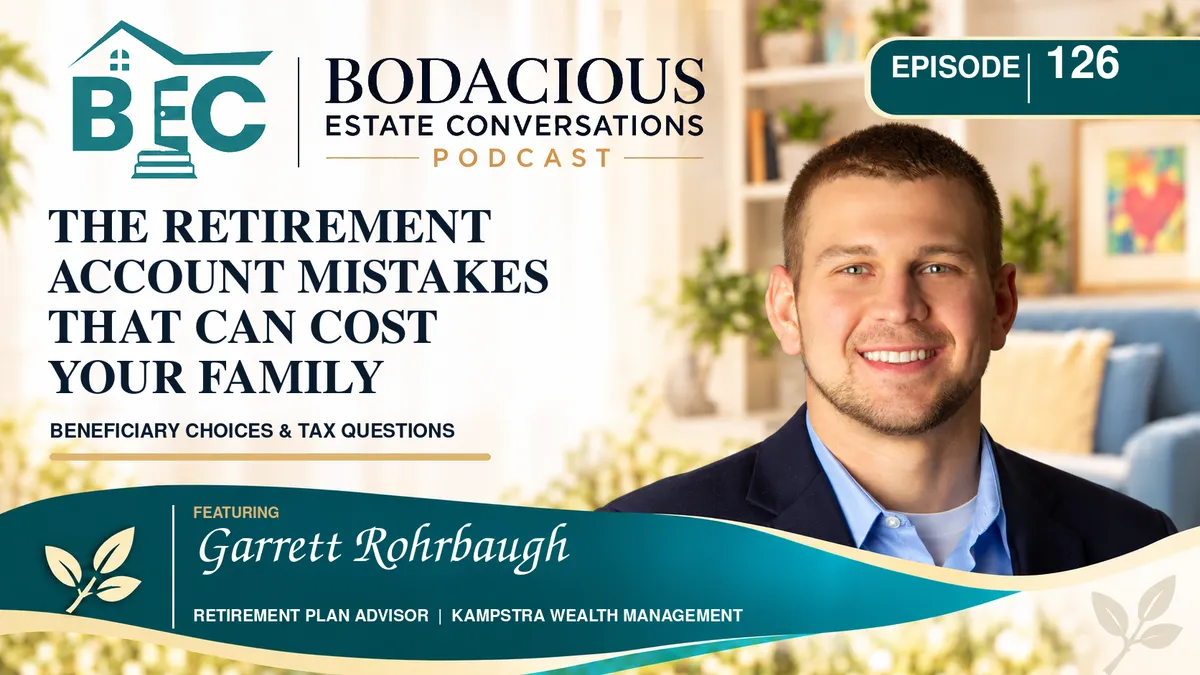
Inherited Retirement Accounts: Beneficiary Mistakes Families Should Review
Bodacious Estate Conversations | Episode 126
Featuring Garrett Rohrbaugh, Retirement Plan Advisor at Kampstra Wealth Management
When someone dies, retirement accounts can raise questions that families may not be ready to answer: Who is named as beneficiary? What paperwork is needed? When must the money be distributed? And could a decision made years ago affect taxes now?
On Episode 126 of Bodacious Estate Conversations, host Kasey King talks with Garrett Rohrbaugh, Retirement Plan Advisor at Kampstra Wealth Management, about beneficiary designations, inherited accounts, executor responsibilities, and the value of reviewing financial records before a crisis.
Start with the account and its beneficiary
A retirement account may have a beneficiary designation on file with the institution that holds it. That designation can affect who receives the account after the owner’s death. It may also mean the executor handles paperwork and coordinates information without controlling when or how the beneficiary takes distributions.
That distinction can surprise families. An executor may be responsible for settling the estate, while the named beneficiary has authority over an account that passes directly to them. The specific process depends on the account, its paperwork, and the institution’s requirements.
Garrett encourages families to slow down when they can. A death is already difficult, and people may feel pressure to make quick decisions. Gathering the documents, identifying the account type, and asking questions can help prevent avoidable confusion.
Review beneficiary choices after major life changes
One mistake Garrett sees is failing to update beneficiaries after events such as marriage, divorce, remarriage, or the birth of a child. An old form can continue to direct an account to someone the owner no longer intends to benefit.
A review can include:
Confirming the beneficiaries listed on each retirement and investment account.
Checking that names and contact information are current.
Asking the institution how to update a designation and whether additional consent or forms are needed.
Reviewing how a trust or an estate named as beneficiary could affect administration and distributions.
Garrett notes that naming a trust or estate can have consequences for how assets are handled. Trusts can provide instructions for distributions, but they are not right for every family. Families should have an estate attorney and tax professional review the plan before changing designations.
Understand that account types are treated differently
The conversation covers three broad account types: tax-deferred retirement accounts, Roth accounts, and taxable investment accounts. Their tax treatment and distribution rules differ.
In general, a beneficiary may face income tax on distributions from a tax-deferred account. Roth accounts are funded with after-tax contributions, but inherited Roth accounts still have distribution requirements. Taxable accounts may receive different treatment, and the details depend on the asset and the owner’s circumstances.
The episode also discusses a general 10-year distribution framework for many inherited retirement accounts, along with exceptions and cases where annual required distributions may apply. The actual rules depend on factors such as the account, beneficiary, and circumstances of the original owner. The IRS likewise explains that inherited IRA rules vary by beneficiary type and other details. Internal Revenue Service
Because a large distribution may affect a beneficiary’s overall tax picture, families should not assume that waiting until the final permitted year is always the best approach. A financial advisor and tax professional can help evaluate timing based on the beneficiary’s situation and current rules.
Keep the executor’s role clear
An executor may need to collect records, provide death certificates, contact institutions, and coordinate with the family’s legal and financial professionals. That work does not automatically give the executor control over an account with a named beneficiary.
Clear records can make this process easier. Garrett recommends thinking ahead about where account information is stored and who should be contacted. Families can benefit from knowing which institutions hold accounts and where to find relevant estate documents.
Executors should also avoid acting beyond their authority. If it is unclear who can make a decision about a particular account, contact the institution and consult the estate attorney before taking action.
Make beneficiary reviews part of routine planning
A beneficiary review does not have to wait until an estate is being settled. Garrett describes reviewing beneficiaries during periodic financial check-ins, including annual reviews of workplace retirement plans.
A useful review can include retirement accounts, taxable investment accounts, wills, trusts, and other estate documents. The goal is to make sure the pieces still reflect the owner’s wishes and that family members know where to find the information.
If charitable giving is part of an estate plan, Garrett also discusses how account type and beneficiary choice may affect the outcome. A charity, trust, or family member may have different tax and administrative considerations. Confirm any charitable or tax strategy with qualified professionals before making changes.
About Garrett Rohrbaugh
Garrett Rohrbaugh is a Retirement Plan Advisor at Kampstra Wealth Management. In the episode, he discusses working with employers and employees on workplace retirement plans and helping families understand account and beneficiary considerations.
Watch or listen to Episode 126
This article is for general educational purposes and is not individualized investment, tax, or legal advice. Retirement account and estate rules can change and depend on the facts of each situation. Consult qualified professionals about your circumstances.
When an inherited home or estate property is part of the transition, Guided Home Prep can help you understand practical next steps. Start a Conversation With Guided Home Prep. No pressure. Just clarity and a plan.