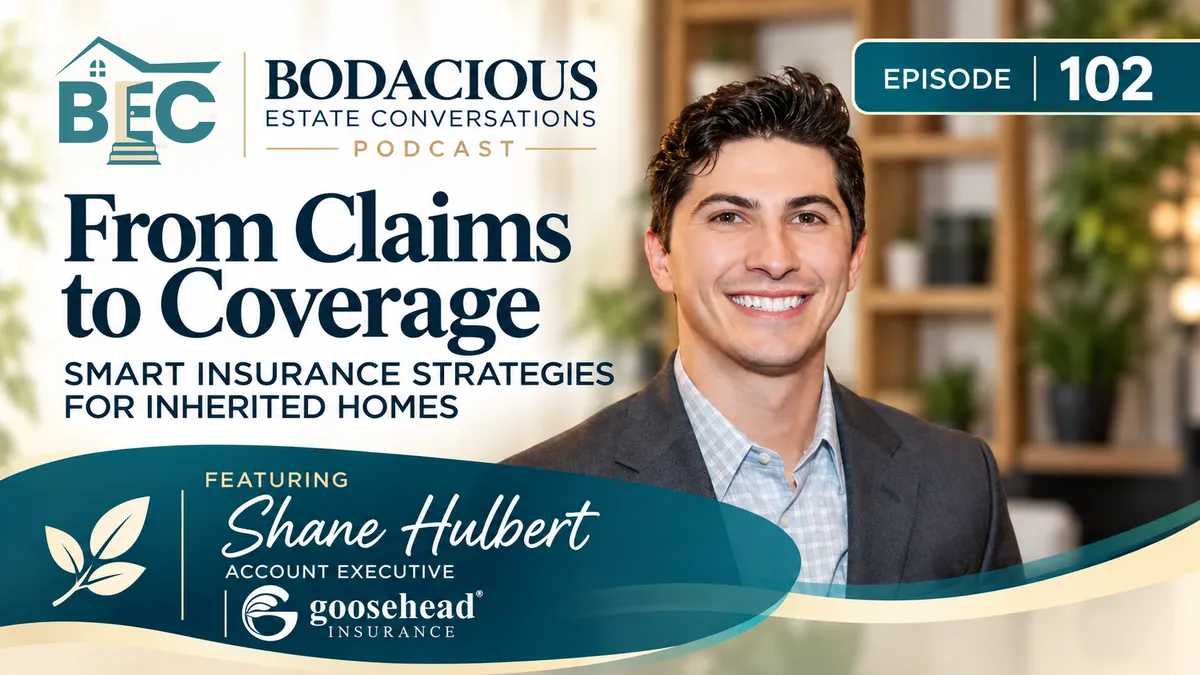
From Claims to Coverage: Insurance Tips for Inherited Homes
Bodacious Estate Conversations | Episode 102
Featuring Shane Hulbert, Account Executive at Goosehead Insurance
When someone passes away and leaves behind a home, families suddenly find themselves responsible for more than just sorting belongings and making decisions about the property. They also need to make sure that home is properly insured.
But what happens when the house is sitting empty? Does the existing homeowners policy still provide coverage? And what should you know before filing an insurance claim?
In this episode of Bodacious Estate Conversations, host Kasey King sits down with insurance professional Shane Hulbert of Goosehead Insurance to discuss the insurance decisions families face when managing inherited homes and estate properties.
From vacant property policies to frozen pipes and unexpected claim denials, Shane explains what homeowners and executors should understand before a costly surprise occurs.
What Happens to Insurance When Someone Inherits a Home?
One of the first questions families face after inheriting property is whether the existing homeowners insurance policy can remain in place.
Shane explains that the answer depends on the insurance company, the policy terms, and what will happen to the home next.
If the property will be sold quickly, the insurer may be able to continue the existing policy with appropriate updates. If the home will remain empty for an extended period, a different type of coverage may be necessary.
The key is to contact the insurance agent, explain the circumstances, and ask what changes are required.
Don't assume that a policy covering an occupied home will automatically provide the same protection after the owner passes away or the property becomes vacant.
Why Vacant Homes Need Special Attention
An empty home presents risks that an occupied home may not.
Without someone living there, a small leak can go unnoticed, heating problems can lead to frozen pipes, and vandalism or property damage may not be discovered immediately.
Shane discusses vacancy provisions that may become relevant after approximately 30 to 60 days, depending on the policy.
A vacant property insurance policy may offer coverage appropriate to the home's circumstances, but the specific protections vary.
Families should ask their agent about:
Fire, wind, and storm damage
Vandalism and malicious damage
Frozen or burst pipes
Water damage
Liability protection
Coverage requirements while the property is listed for sale
Not every vacant property policy covers every risk. The important step is understanding what is included, what is excluded, and whether additional protection is available.
Frozen Pipes: A Common Concern for Pennsylvania Homes
Pennsylvania winters create an additional challenge for inherited homes sitting empty.
When no one is living in a property, it can be tempting to lower the thermostat significantly to reduce utility costs. Unfortunately, frozen or burst pipes can cause extensive damage.
Shane explains that coverage for this type of loss depends on the policy and the circumstances.
If you're responsible for an unoccupied property, speak with the insurer about heating requirements, water shutoff precautions, and whether freezing-related damage is covered.
It's much easier to address these questions before winter damage occurs.
Why Insurance Claims Sometimes Get Denied
One of the biggest surprises homeowners face is discovering that damage they expected insurance to cover isn't covered under their policy.
Shane emphasizes that policies can differ significantly between insurance companies and even between neighbors.
Rather than choosing insurance based on price alone, he encourages homeowners to understand their coverage, exclusions, and deductibles.
He also offers an important reminder when reporting property damage: Be honest about what you know, and don't speculate about the cause.
If you don't know why something happened, say so. Let the appropriate professionals investigate and determine the cause.
Should You File an Insurance Claim?
Just because damage occurs doesn't necessarily mean filing an insurance claim is the best financial decision.
Shane discusses how deductibles and claim history can affect that decision.
As a general rule of thumb used in his practice, he suggests considering whether the damage is at least twice the deductible before deciding to file a smaller claim.
For example, if a homeowner has a $1,500 deductible and repairs cost $1,600, paying out of pocket may be worth considering.
However, every situation is different. The severity of the loss, policy requirements, potential future premiums, and the homeowner's financial circumstances all matter.
Shane also explains that homeowners insurance deductibles generally apply to each covered occurrence, rather than accumulating like a health insurance deductible.
Before deciding whether to file a claim, review your policy and speak with a qualified insurance professional. Report losses within any applicable policy deadlines.
How an Insurance Broker Can Help
Shopping for insurance can be time-consuming, especially when comparing several companies and trying to understand differences in coverage.
Shane explains that independent insurance brokers can compare options from multiple carriers, helping clients evaluate both cost and protection.
For someone managing an inherited property, a knowledgeable agent or broker can also help determine what coverage is appropriate while the family decides whether to sell, rent, or retain the home.
The goal isn't simply finding the lowest premium. It's finding coverage that fits the property's actual risks.
Shane's Biggest Advice for Families Managing an Estate
Toward the end of our conversation, Shane shares two important recommendations.
First, give yourself room to process what has happened. Families don't need to make every decision immediately after losing a loved one.
Second, contact a trusted insurance professional early. Even when the family hasn't decided what to do with the property, an insurance agent can help explain the requirements and options.
While families may have some time to make long-term decisions, they should promptly confirm that coverage remains appropriate and that no notification or vacancy deadlines are missed.
More Than Insurance: Shane's Story
Beyond the practical insurance advice, Shane shares how his background as a college baseball player, martial artist, and student leader shaped his professional career.
We also discuss mentorship, his experience at Penn State York, and his passion for helping others succeed.
His personal experiences with insurance claims helped him appreciate how significantly coverage decisions can affect families.
Watch or Listen to Episode 102
From Claims to Coverage: Smart Insurance Strategies
Need Help Managing an Inherited Home?
Insurance is only one piece of the puzzle when you're responsible for a loved one's property.
At Guided Home Prep, we help homeowners, executors, and families navigate the practical challenges of preparing, maintaining, and selling unwanted real estate in South Central Pennsylvania.
Whether the property needs repairs, a cleanout, ongoing coordination, or a clear plan for what comes next, you don't have to figure it out alone.
No pressure. Just clarity and a plan.
Start a Conversation with Guided Home Prep
Disclaimer: This episode is provided for general educational purposes and is not insurance, legal, or financial advice. Coverage, exclusions, claim requirements, and estate obligations vary. Consult your insurance professional and other qualified advisors about your specific circumstances.